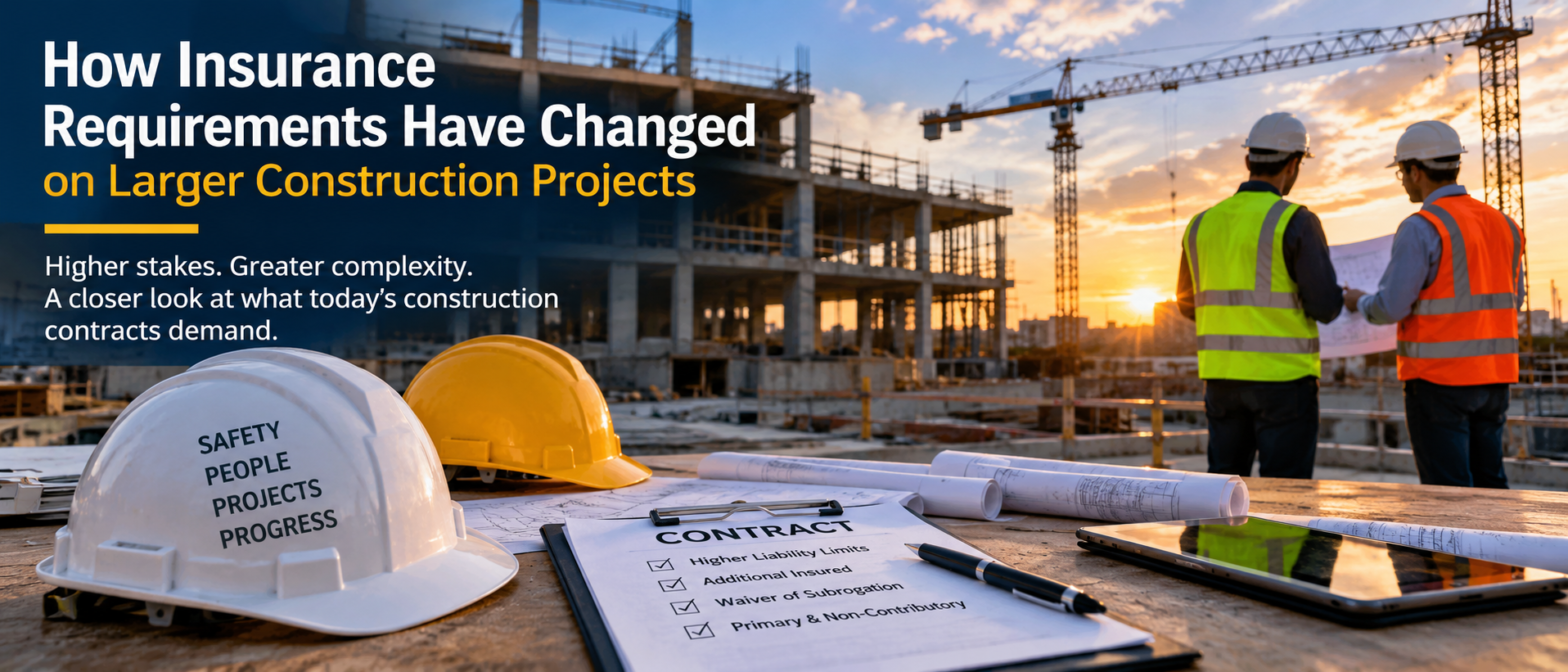
Moving into larger construction projects can be a big step for a contractor. The jobs are larger, the schedules are more involved, and more people may have a financial interest in the work. The contracts are often longer, too, and the insurance requirements can become much more detailed.
A contractor may be used to a simple request. A customer asks for proof of general liability, workers’ compensation, and commercial auto insurance. The contractor calls the insurance broker, gets a certificate, and sends it over.
Then a larger project comes along.
The contract may ask for higher liability limits. It may require several companies to be listed as additional insureds. It may call for a waiver of subrogation or require primary and non-contributory wording. Other requirements may address completed operations, excess liability, or specialized coverage.
At that point, getting onto the job is no longer just a matter of asking your broker for another certificate.
The better question is:
Does the insurance you actually carry satisfy what you agreed to provide?
That distinction matters because a certificate cannot create coverage that is not contained in the underlying policy. If a contract requires a certain limit, endorsement, or coverage provision, putting those words on a certificate does not make the requirement part of the policy.
This is why larger projects can change the timing of the insurance conversation.
Instead of winning the project first and figuring out the insurance requirements afterward, contractors should try to understand those requirements while they are evaluating and bidding the job.
Think about what changes when a contractor moves from smaller commercial jobs into a larger construction project.
There may be an owner, developer, construction manager, general contractor, and many subcontractors. More workers may be on the site. The value of the property may be higher. A serious accident or property damage claim could involve several companies.
Each company wants to manage the risks tied to the project.
The construction contract is one place where those responsibilities are spelled out. The contract may tell a contractor what insurance policies are required, how much coverage must be carried, and which companies need protection under those policies.
This means insurance that worked for one job may not meet the requirements of another.
For example, imagine a general contractor that has carried the same general liability insurance for several years. The contractor has completed many projects and has never had trouble providing a certificate.
Now the company has an opportunity to work on a much larger project.
The new contract requires more than the contractor has seen before. It calls for higher liability limits. The owner and developer must be additional insureds. The contract requires coverage for ongoing and completed operations. It also asks for a waiver of subrogation and primary and non-contributory wording.
There may be nothing wrong with the contractor’s current insurance.
The new job simply has different requirements.
Contractors moving into larger work should review the construction job insurance requirements before making a final commitment. Knowing the requirements early can help keep an insurance issue from becoming a job issue later.
Higher liability limits are often one of the first changes contractors notice on larger projects.
Suppose your commercial general liability policy has a $1 million per-occurrence limit. That may have been enough for many of your past projects.
Then you receive a contract that requires several million dollars in total liability protection.
That does not always mean your general liability policy has to be replaced. Depending on the project and your current insurance program, the additional limit may come from an umbrella or excess liability policy.
The real problem can arise when the contractor does not find out about the higher limit until after the job has been awarded.
Imagine a contractor working on a bid.
The contractor calculates labor and materials. Subcontractor costs are added. Equipment and overhead are included. The contractor works out the expected profit and submits the bid.
Then the contractor gets the good news: the company got the job.
After the award, the project manager asks for a certificate of insurance. The contractor sends the insurance requirements to the broker for the first time.
The broker reads them and finds a requirement for several million dollars of excess liability coverage. The contractor does not currently carry that amount.
Now there is another insurance need tied to the project, but the contractor’s bid has already been accepted.
That can affect the profit the contractor expected to make on the job.
This is why Rich Tygett encourages contractors to send over the insurance requirements before bidding whenever possible. If a larger job requires coverage you do not currently carry, it is better to find out while you are still working on the bid.
Higher limits are not always a problem. Finding out about them too late can be.
For contractors taking on larger jobs, excess liability insurance for contractors may be part of meeting the project’s required limits. The amount and type of coverage needed will depend on the contract and the contractor’s current insurance program.
Many contractors are familiar with the words additional insured.
A project manager may say, “Add us as an additional insured and send a certificate.”
That sounds simple.
On a larger project, the contract may ask for much more.
It might require the owner, developer, general contractor, and other companies to receive additional insured status. It may also state that this protection must apply to ongoing operations, completed operations, or both.
These details matter because additional insured status is based on the policy and its endorsements.
Adding a company’s name to a certificate does not, by itself, create additional insured coverage.
The difference between ongoing and completed operations can be easier to see with an example.
Suppose a contractor is working inside a commercial building.
While the contractor’s crew is on the job, workers are using tools and equipment. Materials are being installed. Other trades are working nearby. Those are exposures connected with work that is still taking place.
Now suppose the contractor finishes the job.
Six months later, there is a claim that property damage was caused by the contractor’s completed work.
The crew is no longer on the site, but the claim is tied to work that has already been completed.
A construction contract may require additional insured protection for both situations.
This is why contractors need to look beyond a request that simply says, “Additional insured required.”
The exact contract wording and the insurance endorsements matter.
A certificate of insurance shows information about insurance coverage. It does not change the insurance policy.
That difference is especially important on larger construction projects.
Suppose a project manager emails a contractor and says:
“Add the owner as an additional insured and send us a new certificate.”
The contractor forwards the email to the broker.
When the broker reads the full contract, however, it says the owner and general contractor both need additional insured status. It also requires protection for ongoing and completed operations.
Now this is not just a request to type another name on a certificate.
The broker needs to review the policy and endorsements to see if the contractor’s insurance meets the requirement.
If the policy does not provide something the contract requires, words on the certificate cannot create that protection.
This is one reason contractor certificate of insurance requirements should be reviewed along with the policies behind the certificate.
A certificate should reflect the insurance that is actually in place. It should not be treated as a way to add coverage that the policy does not contain.
For contractors, that difference matters most when a project is about to start. A rejected certificate can hold up access to the job site. If the real problem is an insurance requirement that was never addressed, getting an acceptable certificate may involve more than changing a document.
A waiver of subrogation is another requirement contractors may see on larger projects.
The phrase sounds technical, but the basic idea can be explained in plain language.
After an insurance company pays a covered claim, there are times when the insurer may have the right to seek money from another party that caused or contributed to the loss. That process is called subrogation.
A waiver of subrogation can limit certain recovery rights against a person or company named in the requirement. The actual effect depends on the policy and endorsement.
A construction contract may require a waiver in favor of the owner, general contractor, or another party.
Imagine that a contractor is getting ready to start a project on Monday.
On Friday afternoon, the project manager sends an email:
“We also need a waiver of subrogation in favor of the owner and GC.”
The contractor may think this means the broker only needs to add another line to the certificate.
But the request may require more than a certificate change.
The broker needs to look at the contract and the policies involved. The broker may need to determine which policies require the waiver and if the policy or endorsement supports what the contract asks for.
The certificate comes after that review.
This is another example of why contractors should not wait until the day before work starts to look closely at the insurance requirements.
Larger construction contracts may also require insurance to be primary and non-contributory.
This requirement is different from a liability limit.
A liability limit deals with how much insurance is available, subject to the terms of the policy.
Primary and non-contributory wording deals with how applicable insurance is expected to respond compared with certain other insurance available to an additional insured.
In general, primary wording addresses the expectation that the contractor’s applicable coverage will respond before certain other insurance available to the additional insured.
Non-contributory wording generally addresses if certain insurance available to the additional insured is expected to share in that loss.
The actual policy and endorsements control how the insurance works.
Consider a contractor that has the liability limits required by the project. The owner has been provided additional insured status. The contractor sends the certificate and expects it to be approved.
Instead, the project manager rejects it.
The contract also requires primary and non-contributory treatment, and that requirement has not been confirmed.
If the project starts next month, there may be time to work through the issue.
If the contractor is expected on the job tomorrow morning, the same issue can delay the start of work.
The insurance requirement did not suddenly appear. It was already in the contract.
It simply was not addressed early enough.
On larger projects, looking at one insurance requirement at a time can give a contractor an incomplete picture.
Suppose a contract requires $1 million of general liability coverage plus several million dollars of excess liability.
The contractor checks the limits. They look fine.
But the contract also requires the owner, developer, and general contractor to be additional insureds. It requires protection for ongoing and completed operations. It asks for a waiver of subrogation. It also requires primary and non-contributory wording.
Meeting the limit does not mean all of the other requirements have been met.
The same is true of the certificate.
Seeing the owner’s name on a certificate does not prove that every part of the contract has been satisfied.
The requirements have to be compared with the contractor’s insurance program as a whole.
Contractors should also remember that insurance requirements may appear in more than one part of a construction contract. A section titled “Insurance” may not be the only place where insurance duties are described.
This is why sending the full requirements or contract to your broker can be helpful.
A one-page certificate request may not tell the whole story.
The best time to find an insurance requirement you do not currently meet is before you have agreed to provide it.
Imagine two contractors looking at similar projects.
The first contractor gets the insurance requirements before finishing the bid and sends them to the broker.
The broker reviews the required limits and coverage. The broker also finds additional insured requirements, a waiver of subrogation, primary and non-contributory wording, and another type of insurance the contractor does not currently carry.
The contractor now has useful information and time to understand what the job requires before submitting the final bid.
The second contractor does not review the insurance section. The contractor assumes the broker can handle it after the job is awarded.
The contract gets signed.
Then the certificate request arrives.
Only at that point does the second contractor find out about the extra requirements.
Both contractors may be able to meet the project’s insurance requirements. The difference is that the first contractor knew about them before making the final commitment.
There may also be a requirement that does not seem to fit the work a contractor is doing.
Before the contract is signed, there may be time to discuss that requirement with the other party. The other party may or may not agree to change it.
After the contractor has agreed to the contract, there may be fewer choices.
If you want your broker to review a project, send the full insurance requirements or contract when possible. Include the project description, expected start date, requested limits, certificate instructions, and any special wording or endorsement requests you received.
The more complete the information is, the easier it is to compare the job requirements with the insurance you already have.
Contractors often focus on certificates because a certificate may stand between the crew and the job site.
The employees are ready.
Equipment has been scheduled.
Subcontractors may already be lined up.
Then the project manager says, “Your certificate has not been approved. You can’t start yet.”
At that point, the certificate feels like the problem.
But the real problem may have started much earlier.
A better order is simple:
Read the job requirements. Review the policies and endorsements. Address any missing requirements. Then issue the certificate.
When this happens early, the certificate is evidence of an insurance program that has already been checked against the project requirements.
When it happens at the last minute, the contractor and broker may be trying to solve coverage questions while a crew is waiting to start work.
Larger projects often come with more detailed contracts. Contractors can save themselves trouble by treating insurance review as part of preparing for the job, rather than something that happens after the job has already been awarded.
Moving into larger construction projects can bring larger contracts and new opportunities. It can also bring insurance requirements that a contractor has not dealt with on previous jobs.
Higher liability limits may require excess coverage. Additional insured requirements may include several companies and may apply to ongoing and completed operations. The contract may require a waiver of subrogation. It may also call for primary and non-contributory wording.
The main lesson is simple: do not judge the insurance requirements by the certificate alone.
The certificate cannot add coverage that the policy does not provide. The policy, endorsements, limits, and contract requirements all need to line up.
It is much better to find an insurance issue while you are reviewing the job than after the contract has been signed, the crew has been scheduled, and the project manager is waiting for an approved certificate.
If you have a larger construction project coming up, send us the insurance requirements before you bid or start work. Integrated Commercial Insurance Solutions, Inc. can review the requirements with you and help you see how your current insurance program lines up with the job.
Request a quote from Integrated Commercial Insurance Solutions, Inc. or call 800-922-9721.
Getting the insurance questions answered early can help you approach the project knowing what the contract requires and what needs to be in place before work begins.
Why do larger construction projects require higher liability limits?
Larger projects can involve higher property values, more workers, more subcontractors, and more organizations with an interest in the project. Owners, developers, and general contractors may require higher limits as part of the way they manage and allocate project risk.
What happens if a construction project requires more liability coverage than I currently carry?
Your broker can compare the required limits with your current insurance program. Depending on the requirement and your existing policies, umbrella or excess liability coverage may be one way to provide additional limits. It is better to identify this need before the final bid or contract commitment.
What does additional insured mean on a construction project?
Additional insured status generally provides certain insured protections to another party under the contractor’s policy, subject to the policy and endorsement language. A contract may require additional insured status for an owner, developer, general contractor, or other organization.
What is the difference between ongoing and completed operations?
Ongoing operations relate to work while it is being performed. Completed operations relate to claims connected with work after it has been completed. A construction contract may require additional insured protection for one or both.
Can a certificate of insurance make someone an additional insured?
A certificate by itself does not create additional insured coverage. The contractor’s actual policy and applicable endorsements must support the additional insured requirement.
What is a waiver of subrogation in construction insurance?
After paying a covered claim, an insurer may have certain rights to seek recovery from another responsible party. A waiver of subrogation can limit certain recovery rights against specified parties, subject to the applicable policy and endorsement.
What does primary and non-contributory mean?
Primary wording generally addresses how the contractor’s applicable insurance responds before certain other insurance available to an additional insured. Non-contributory wording generally addresses whether certain insurance available to the additional insured is expected to contribute to the loss. The actual policy and endorsements determine how coverage applies.
When should I send project insurance requirements to my broker?
Whenever possible, send them before submitting your final bid or signing the contract. Early review gives you time to compare the project’s requirements with your current insurance and identify limits, coverage, or endorsements that may need attention.
This article is a collaboration between IC Insurance Solutions, Inc and OpenAI’s ChatGPT. Created on Sep 15, 2026, it combines AI-generated draft material with IC Insurance’s expert revision and oversight, ensuring accuracy and relevance while addressing any AI limitations.
https://www.irmi.com/term/insurance-definitions/additional-insured
https://www.americanbar.org/groups/construction_industry/publications/under_construction/2021/summer2021/a-primer-on-waivers-of-subrogation/
https://www.law.cornell.edu/wex/subrogation