You get a chance to bid on a new construction job. The project looks like a good fit.
You know how many workers you will need. You have a good idea of the material costs. You know which equipment you will use and which subcontractors you may need. You start putting the numbers together so you can decide what to bid and what you expect to make on the job.
Then you read the insurance requirements.
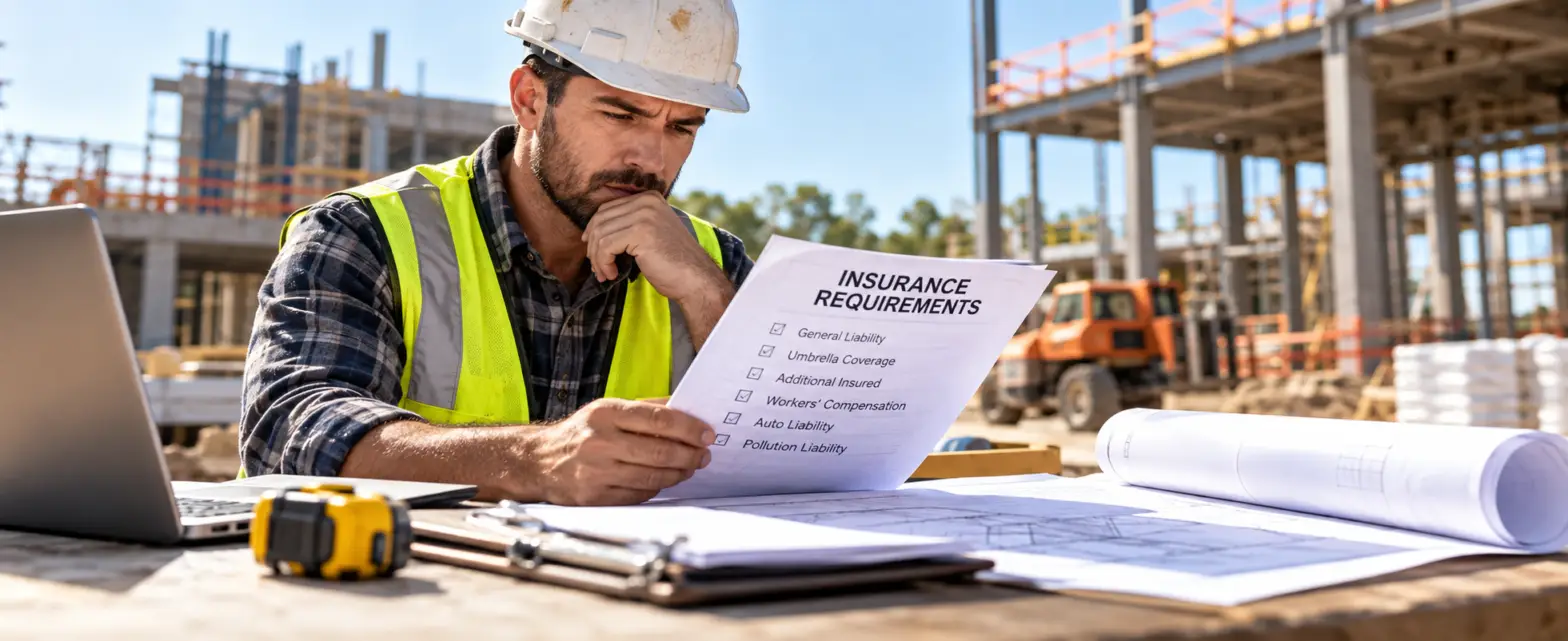
The contract asks for higher general liability limits than you currently carry. It also requires $5 million in umbrella or excess liability coverage. The owner wants additional insured status, a waiver of subrogation, and primary and noncontributory wording.
You may even see coverage you do not currently carry, such as pollution or professional liability.
Now you have another part of the job to figure out.
Insurance requirements can affect what it takes to complete a project. If you wait until after you win the job to review them, you may find out that you need higher limits, new coverage, or policy changes that were not included in your bid.
The better time to answer these questions is before you bid.
An early review lets you compare the job requirements with your current insurance. You can find gaps, ask questions about requirements that may not fit your work, and learn what it may take to meet the remaining requirements before you agree to the job.
Here are some of the main insurance questions contractors should ask before submitting a bid.
Start with the contract.
You need to know what the owner or general contractor expects you to carry before you can determine if your current insurance meets the requirements.
This can take more work than reading one page.
Insurance requirements may appear in several parts of a construction contract. One section may list general liability limits. Another may explain what is required from your subcontractors. An insurance exhibit may list required endorsements. Other requirements may appear in sections that deal with the work you will perform.
Depending on the job, the contract may require general liability, workers’ compensation, commercial auto, umbrella or excess liability, professional liability, pollution liability, or other coverage.
It may also require additional insured status, primary and noncontributory wording, or a waiver of subrogation.
For example, think about a general contractor bidding on a commercial renovation.
The contractor reads the insurance exhibit and sees limits that look normal. Based on that page, the contractor thinks the current insurance will work.
But another part of the contract includes requirements for subcontractors and completed operations. Those provisions also need to be reviewed.
This is why you should not assume that every job will have the same insurance requirements as your last project. Each contract can be different.
You also should not assume that every item in the contract means you need a new policy. Start by finding out what the job requires. Then compare those requirements with the insurance you already carry.
Our page on construction job insurance requirements explains what contractors should look for when reviewing a project.
General liability is one of the first coverages many contractors check.
A contractor may carry limits that have worked for years. Then a larger project comes along and asks for more.
Suppose your current policy provides a certain level of general liability coverage, but a new project requires higher limits. You need to know that before you submit your bid.
Start by comparing the limits in the contract with the limits on your policy.
If your current limits are lower, talk with your insurance broker about the requirement. Find out what options may be available and what would need to happen to meet the contract.
Do not assume the problem can be fixed by changing the certificate of insurance.
A certificate shows evidence of the insurance you have. It does not give you higher limits or add coverage that is missing from your policy.
For example, if your policy has a $1 million limit and the contract requires more, a certificate cannot turn the policy into a higher-limit policy. The insurance behind the certificate must support what the certificate shows.
Having enough general liability limits does not mean every risk on the job is covered. General liability policies have exclusions, conditions, and endorsements. The type of work you perform can also affect how the policy responds. A contractor can have a general liability policy and still have coverage gaps.
You can read more about how this coverage works on our contractor general liability insurance page.
Larger projects may require more liability coverage than your main policies provide.
This is where umbrella or excess liability may become part of the discussion. A contract may require several million dollars in limits above certain underlying policies. The exact way the coverage works depends on the policy and insurance program.
For a contractor preparing a bid, the first question is simple: Do I already have the limits this job requires?
If the answer is no, you need to find out what it will take to meet the requirement.
Think about a contractor who has been in business for several years. The contractor finds a good commercial project. The crew can handle the work. The contractor checks material and equipment costs, gets numbers from subcontractors, adds overhead and expected profit, and submits a bid.
The contractor wins the job. Then the client asks for insurance documents. The contractor learns that the contract requires $5 million in excess liability coverage, which is not part of the current insurance program.
At that point, the contractor has already committed to a number. Even if the required coverage is available, it may create an expense that was not included in the original bid. That can reduce the profit the contractor expected to make.
Now change the timing. Suppose the contractor sends the insurance requirements to the broker before bidding. The excess liability requirement is found early. The contractor can review the options and learn what meeting the requirement may involve.
That information can then become part of the bid. The requirement did not change. What changed was when the contractor learned about it. Finding it before the bid gives the contractor more time to deal with the requirement before making a commitment.
Some insurance requirements may be open to discussion. Others may not be.
The answer may depend on the owner, general contractor, type of project, contract, and work you will perform.
Suppose a contractor is hired only to perform construction work. The contractor is not doing design work or providing professional services, but the contract still asks for professional liability coverage.
That gives the contractor a good reason to ask why the coverage is required.
It may apply to the job. But the owner may also be using a standard contract that includes the same insurance section for many types of contractors. The contractor can ask whether the requirement applies to this specific scope of work.
The best time to have that conversation is before signing the contract or committing to the job. If you have already agreed to provide the coverage, your position may be very different.
The same approach can apply to limits and other insurance terms. A client may agree to change a requirement, or the client may say the requirement must stay.
Do not simply cross out a requirement or decide that it does not apply. Discuss it with the right people. If a requirement is changed or waived, get that change in writing.
Construction contracts often include insurance terms that go beyond dollar limits.
You may see requirements for additional insured status, a waiver of subrogation, or primary and noncontributory wording. These terms can affect how coverage works between the parties on a project.
For example, an owner or GC may require additional insured status under your general liability policy. The contract may also require certain coverage to be primary and noncontributory when the policy supports it. A waiver of subrogation may also be required.
The details depend on the policy, endorsements, and contract.
For contractors, the main point is that these are not just words to put on a certificate. The policy and endorsements must support the requirement.
Suppose a client asks you to add special wording to the certificate. If your policy does not provide what the client is asking for, putting those words on the certificate does not change the policy.
The same rule applies to limits. A certificate cannot make your limits higher. It cannot remove an exclusion. It cannot add coverage that your policy does not contain.
When a client sends a long certificate request, the real question is not just, “Can I get the certificate?” A better question is, “Does my actual insurance meet the job requirements?” Answer that question first.
Not every insurance problem involves limits.
Sometimes a contract requires a type of coverage that is not part of your current insurance program. It might require pollution liability, professional liability, builders risk, inland marine, or another type of coverage.
If that happens, do not assume that you need to add the coverage right away. You also should not assume that you can ignore it. Start by finding out why it is being requested.
Professional liability is one example. A contractor who provides certain design or professional services may have a different exposure from a contractor who only performs work from plans provided by someone else.
Pollution liability is another example. A contractor does not have to be an environmental cleanup company for pollution issues to matter. Some construction work can create pollution exposures that may not be handled the way a contractor expects under a general liability policy.
Tools and equipment can create similar confusion. A contractor may think, “I have general liability, so I’m covered.” But general liability is not designed to protect every piece of property a contractor owns, rents, transports, or uses.
When unfamiliar coverage appears in a contract, ask questions. Why is the coverage required? Does it apply to your work? Do you already have coverage that meets the requirement? If not, what options are available?
Answering those questions before the bid can prevent a harder conversation after the project starts.
There is no single answer.
A request involving insurance you already carry is very different from a request that requires higher limits, a new endorsement, underwriting approval, or a new policy.
The timing can depend on the type of coverage, your operations, the project details, and the limits being requested. The insurance company may also need more information before approving a change.
This is why contractors should separate two different requests: getting a certificate and changing insurance coverage.
Suppose your current insurance already meets all of the project requirements. You may simply need the proper documents.
Now suppose the review shows that you need higher limits or a type of coverage you do not have. That is a different request and may take more time.
If you send the requirements the afternoon before work is supposed to begin, there may be little time to deal with a coverage issue. You may have a crew scheduled. Equipment may already be lined up. The client may be waiting for proof of insurance before allowing anyone onto the site.
That creates pressure that may have been avoided by reviewing the requirements earlier.
Send the requirements as soon as you receive them. If you know the bid date and expected start date, give your insurance broker those dates too. That helps everyone understand the schedule and how much time is available to address any issues.
General contractors also need to think about the people working under them.
You may have your own insurance in good order, but what about your subcontractors?
You may know a subcontractor well. You may have worked together for years. You may have a W-9 on file and an old certificate of insurance. That does not mean the subcontractor’s current insurance meets your requirements.
Policies renew at different times, and coverage can change. A certificate collected last year may not tell you what is in place now.
At IC Insurance Solutions, we look at subcontractor risk in three parts: verification, documentation, and risk transfer.
Verification means checking the insurance the subcontractor is required to carry. This may include general liability, workers’ compensation, commercial auto, and excess coverage. Renewal dates should also be tracked.
Documentation means keeping signed subcontractor agreements, certificates, required endorsements, and other records in an organized file.
Risk transfer deals with how responsibility is handled between the general contractor and subcontractor. Depending on the contract, this may include required limits, additional insured status, indemnification language, and other terms.
A W-9 by itself does not handle these issues.
Missing subcontractor insurance records can also create problems during an insurance audit. Missing workers’ compensation coverage can create another serious exposure for a general contractor.
If your bid depends on subcontractors, think about these requirements before the job begins.
Our subcontractor insurance requirements page explains how contractors can approach this part of the job.
You do not need to become an insurance expert to bid a job.
Your broker should help you read the requirements and compare them with your current insurance. But the broker needs the right information.
Start by sending the actual insurance requirements. If they appear in several parts of the contract, send those sections or the full contract when needed.
Also explain the work you will perform. Your broker may need to know the project location, start date, scope of work, required limits, use of subcontractors, and any unusual work involved.
Make sure the broker knows the bid deadline too.
Instead of asking only, “Can you send me a certificate?” ask: “Can you review these job requirements and tell me how they compare with my current insurance?”
That question gives you more useful information.
You can find out which requirements you already meet. You can identify missing limits or coverage. You can learn whether endorsements may be needed. You can also spot requirements that should be discussed with the client before you agree to the work.
The goal is not to add insurance simply because the contract has a long list of requirements. The goal is to know what you are agreeing to before you put your number on the job.
Contractors spend a lot of time getting a bid right.
You calculate labor and materials. You check equipment costs. You get numbers from subcontractors. You account for overhead. You think about the schedule and the profit you expect to make.
Insurance should be part of that same process.
Think about two contractors bidding similar projects.
One contractor sends the insurance requirements to the broker before submitting the bid. The broker finds a higher excess liability requirement and another coverage question. The contractor has time to review the issues, speak with the client when needed, and find out what meeting the requirements may involve.
The other contractor bids the project first. After winning the job, that contractor sends a certificate to the client. The certificate is rejected because the existing insurance does not meet several parts of the contract.
Now the contractor has to solve the insurance problem after agreeing to the job.
Reviewing the requirements early does not make those requirements go away. It gives you time to address them before they become a last-minute problem.
Before you bid, find out what the project requires. Compare those requirements with your current policies. Look for missing limits, endorsements, or coverage. Ask questions about requirements that do not seem to fit your work. If something needs to change, find out what that involves before you commit to the project.
Most of all, do not wait for a rejected certificate to find out that your insurance does not match the contract.
If you have a job you are preparing to bid, send us your job requirements and we’ll review them with you.
Integrated Commercial Insurance Solutions, Inc. works with contractors to review job requirements, identify insurance issues, and help determine what may be needed before the job begins.
To request a quote, visit https://icinssolutions.com/request-a-quote/ or call 800-922-9721.
Should contractors review insurance requirements before bidding a job?
Yes. Reviewing the requirements before bidding can help you identify higher limits, missing coverage, required endorsements, and other insurance obligations before you commit to the project.
What insurance should contractors look for in a construction contract?
Requirements vary by project. They may include general liability, workers’ compensation, commercial auto, umbrella or excess liability, pollution liability, professional liability, and other coverage. Contracts may also require additional insured status, primary and noncontributory wording, or a waiver of subrogation.
Can a certificate of insurance increase my coverage limits?
No. A certificate provides evidence of existing insurance. It cannot increase your limits, remove an exclusion, or create coverage that is not provided by the underlying policy.
What happens if a job requires higher liability limits than I currently carry?
Talk with your insurance broker before submitting the bid. The broker can compare the contract requirements with your current insurance and help determine what options may be available to meet the required limits.
What if a project requires umbrella or excess liability coverage?
First, determine whether your current insurance program already meets the requirement. If it does not, find out what would be required to satisfy the contract before you finalize your bid.
Can construction insurance requirements be negotiated?
Some requirements may be open to discussion, while others may not be. This depends on the contract, project, client, and scope of work. If a requirement does not appear to fit your operations, ask about it before signing the contract and document any agreed changes in writing.
What does additional insured status mean for a contractor?
A construction contract may require an owner, general contractor, or another party to receive additional insured status under a contractor’s policy. The actual protection depends on the policy and applicable endorsement, so the requirement should be compared with the coverage you carry.
How long does it take to change insurance coverage for a new job?
There is no standard timeframe. A request for documentation on coverage you already carry is different from a request that requires underwriting approval, higher limits, a new endorsement, or a new policy. Send the requirements to your broker as early as possible.
Do subcontractors need to meet insurance requirements too?
General contractors often need to establish and document insurance requirements for their subcontractors. This may involve verifying general liability, workers’ compensation, commercial auto, or excess coverage and maintaining certificates, endorsements, and signed subcontractor agreements.
What should I send my insurance broker before bidding?
Send the actual insurance requirements and relevant contract sections. You should also provide information about the scope of work, project location, anticipated dates, required limits, subcontractor use, unusual operations, and the bid deadline.
This article is a collaboration between IC Insurance Solutions, Inc and OpenAI’s ChatGPT. Created on Sep 30, 2026, it combines AI-generated draft material with IC Insurance’s expert revision and oversight, ensuring accuracy and relevance while addressing any AI limitations.
ConsensusDocs – Construction Contract Resources
ConsensusDocs publishes construction contract guidance developed with input from organizations representing owners, contractors, subcontractors, and other construction participants. Its resources are useful for professionals who want a broader contract and risk-allocation perspective on insurance, indemnification, and project responsibilities.
https://www.consensusdocs.org/
International Risk Management Institute (IRMI) – Construction Risk Management
IRMI is a long-established technical resource for insurance and risk-management professionals. Its construction material provides deeper discussion of contractual risk transfer, additional insured issues, construction insurance, and related subjects.
Associated General Contractors of America – Risk Management
AGC provides construction-industry education and resources addressing risk, contracts, safety, and business practices from the contractor’s point of view. Its risk-management material complements the insurance discussion with a broader project-risk perspective.