You know how to run a construction job. You know how to manage workers, hire subcontractors, and keep a project on schedule. But when someone hands you a contract full of insurance terms, things can get confusing.
Maybe a property owner wants to be named as an additional insured. Maybe a general contractor needs a certificate of insurance before you can start work. Or perhaps a new job requires more liability coverage than you currently have.
What do these terms mean? More importantly, how do they affect your business?
Insurance terms are more than words in a contract. They can affect which jobs you can take, how claims are handled, and how much risk your business faces.
The good news is that you don’t need to be an insurance expert. You just need to understand the terms that come up most often.
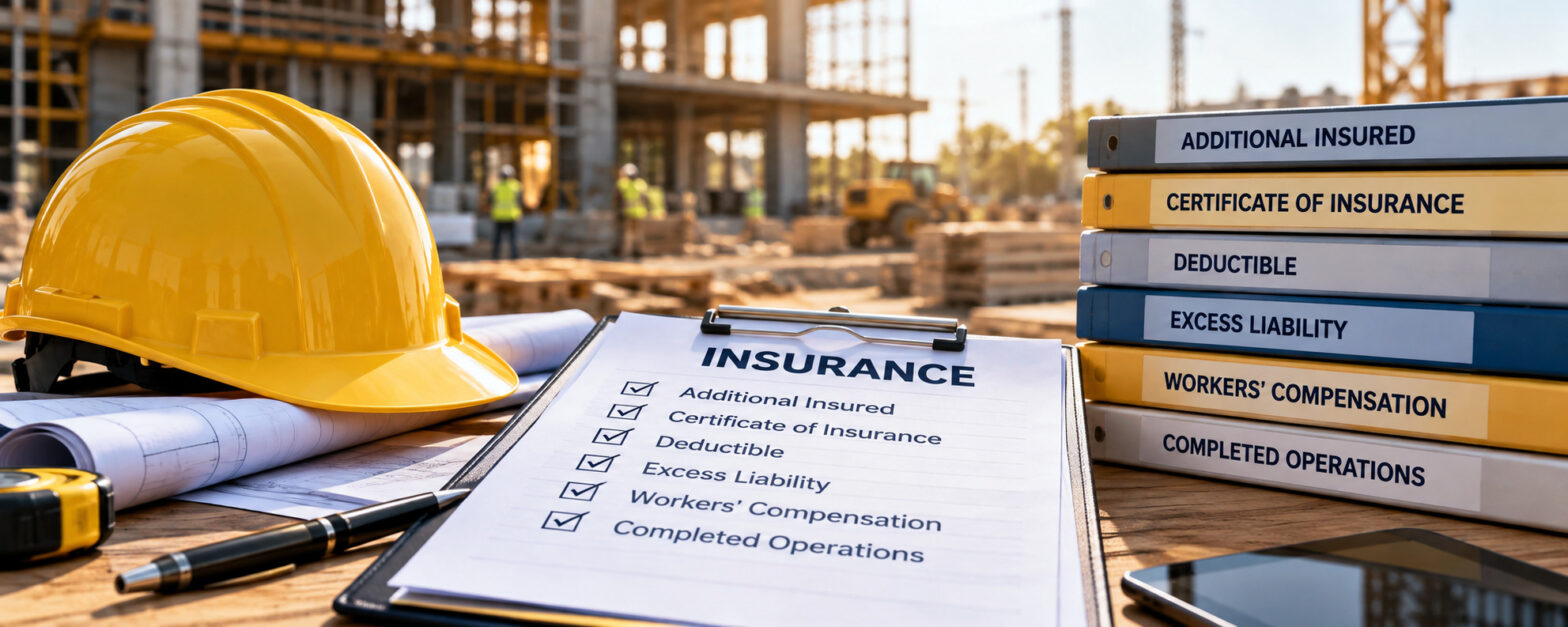
Here are six insurance terms every contractor should know, along with simple examples of how they apply to construction work.
An additional insured is a person or business that receives certain liability protection under another company’s insurance policy.
This is common in construction because several companies often work on the same project.
For example, a property owner hires a general contractor. That contractor hires plumbers, electricians, and other subcontractors. Each company has its own work to do, but if something goes wrong, more than one business could face a claim.
That’s why a property owner may ask to be named as an additional insured on the general contractor’s liability policy.
The owner wants protection against certain claims connected to the contractor’s work.
Let’s say you’re a general contractor working on a commercial building.
You hire a plumbing subcontractor. During the job, the plumber makes a mistake that causes water damage.
The property owner files a claim against both the plumber and your company.
If your company is properly named as an additional insured on the plumber’s policy, that policy may help protect your business against certain claims tied to the plumber’s work.
However, additional insured coverage does not protect you from every possible claim.
The protection depends on the policy, the type of work, and what caused the damage.
You also need the right policy wording or endorsement. An endorsement is a document that adds to or changes an insurance policy.
Simply putting your company’s name on a certificate of insurance does not always provide additional insured protection.
When you hire subcontractors, you need to know what insurance they carry and if their policies can protect your company when their work causes a covered loss.
This is one reason written subcontractor agreements matter.
A well-written agreement explains who is responsible for certain risks and what insurance each subcontractor must carry.
If you use subcontractors often, understanding subcontractor insurance requirements can help you set clear expectations before work begins.
Before starting a job, ask your insurance advisor to review the additional insured requirements in the contract.
That way, you’ll know if the policy provides the protection the contract requires.
A certificate of insurance, or COI, is a document that shows basic information about your insurance.
It usually lists your insurance company, policy types, coverage limits, and policy dates.
Many contractors need certificates before they can start a job.
A property owner may ask for one before allowing you onto the site. A general contractor may also need certificates from every subcontractor.
The certificate helps show that certain insurance policies are in place.
But it doesn’t tell the whole story.
Imagine you win a commercial construction job.
The owner asks for a certificate showing $1 million in general liability coverage and $2 million in excess liability coverage.
You already have general liability insurance, so you call your insurance provider and ask for the certificate.
Then you learn that you don’t have excess liability insurance.
Your insurance provider cannot simply add that coverage to the certificate. You must first have the required insurance in place.
A certificate of insurance cannot add coverage that your policy does not provide.
This matters because contractors sometimes think a certificate is all they need to meet a job’s insurance requirements.
But the actual insurance policy must meet those requirements.
A property owner may reject your certificate if the coverage limits are too low or a required policy is missing.
The owner may also ask for an endorsement that hasn’t been provided.
Even a small mistake, such as listing the wrong company name, can delay the start of a job.
You should also know the difference between a certificate holder and an additional insured.
A certificate holder is the person or business that receives the certificate. An additional insured has certain rights under the insurance policy.
These are two different things.
Before requesting a certificate, send your insurance advisor the full insurance requirements for the job.
Your advisor can review them and check them against your current policies.
Our information on contractor certificate of insurance requirements explains why this review matters.
The goal isn’t just to get a certificate. It’s to make sure the insurance behind it meets the job’s requirements.
A deductible is the amount you must pay toward a covered loss before your insurance company pays its share, based on your policy.
Most contractors have dealt with deductibles before.
You may have one on your commercial auto policy or on insurance that covers your tools and equipment.
Knowing the amount matters when something goes wrong.
Let’s say you own a piece of construction equipment.
One day, it gets damaged in an accident.
The repair cost is $10,000, and your equipment policy has a $1,000 deductible.
If the full loss is covered, you pay $1,000. Your insurance company pays the remaining $9,000.
That’s how a basic deductible works.
But different policies may have different deductibles.
Your truck insurance might have a $500 deductible, while your equipment policy has a $2,500 deductible.
You need to know what applies to each policy.
Construction companies depend on trucks, tools, and equipment to keep working.
If something breaks or gets damaged, you may need to repair or replace it quickly.
Your deductible affects how much money your company must have available when a covered loss happens.
A higher deductible may lower your insurance premium, but it can also mean paying more out of pocket after a claim.
A lower deductible may reduce that cost when a claim happens, but the premium may be higher.
Some policies also have a self-insured retention. This is similar to a deductible, but the rules can be different.
Ask your insurance advisor to explain it if you see that term in your policy.
One more thing: paying a deductible does not mean every loss is covered.
If your policy excludes a type of damage, the deductible won’t change that.
Know your deductible and what your policy covers before you need to file a claim.
Excess liability insurance adds more liability coverage limits above certain other insurance policies.
This type of insurance often matters when contractors take on larger jobs.
You may have worked for years with the same general liability limits. Then a property owner gives you a contract that requires much more coverage.
You may need excess liability insurance to meet that requirement.
Let’s say your general liability policy has a $1 million limit for each covered claim.
Now you’re bidding on a commercial project, and the owner requires $5 million in liability limits.
Your current general liability policy alone isn’t enough.
You may be able to meet the requirement by adding a $4 million excess liability policy above your $1 million general liability policy.
The exact arrangement must meet the contract’s requirements and the terms of both policies.
Think of general liability as the first layer of protection.
If a covered claim goes above that policy’s available limit, the excess policy may help pay the amount above it.
But excess liability does not cover everything.
If your general liability policy excludes certain work, you should not assume your excess policy will cover it.
The terms of both policies matter.
You may also hear the term umbrella insurance.
Both umbrella and excess liability insurance can provide higher limits, but they are not always the same.
Excess liability usually adds limits above certain existing policies.
Umbrella insurance may cover some claims that other policies do not, depending on its terms.
Your insurance advisor can explain how each option works for your business.
Imagine you bid on a large renovation job.
You figure out your labor, materials, equipment, and subcontractor costs. You also plan how much profit you expect to make.
Then you win the job.
Only afterward do you find out that the owner requires $5 million in liability limits.
You have only $1 million.
Now you need more insurance, but you didn’t plan for that expense.
That could reduce the profit you expected from the job.
Some owners may agree to change their insurance requirements. Others may not.
Either way, it’s better to know what the contract requires before you submit your bid.
Reviewing the insurance requirements for construction jobs can help you understand what coverage a project may need.
When you know the insurance requirements early, you can plan for them before agreeing to the work.
Workers’ compensation insurance generally helps employees who suffer covered injuries or illnesses because of their work.
Depending on state law and the policy, it may help pay for medical care and part of the worker’s lost wages.
Construction work carries many risks.
Workers climb ladders, use power tools, lift heavy materials, and operate equipment.
Even careful workers can get hurt.
Workers’ compensation helps address certain costs when a covered workplace injury happens.
General liability and workers’ compensation cover different types of risks.
General liability usually deals with certain injuries or property damage involving other people or businesses.
Workers’ compensation generally deals with covered injuries and illnesses involving employees.
For example, if a visitor trips over construction materials and gets hurt, general liability may apply.
If one of your employees falls from a ladder while working, workers’ compensation may apply.
The exact answer depends on the facts and the policies.
You should not expect general liability insurance to replace workers’ compensation.
Now imagine you’re a general contractor.
You hire a framing subcontractor to work on a commercial building.
One of the subcontractor’s workers falls from a ladder and suffers a serious injury.
You thought the subcontractor had workers’ compensation insurance, but you never checked.
Now you find out that the subcontractor does not have the coverage you expected.
Depending on state law and the worker’s legal status, your company could face added responsibility.
This is why checking subcontractor insurance is so important.
You should not assume someone has insurance just because they’ve been in business for years.
A good subcontractor insurance process has three parts: verification, documentation, and risk transfer.
Verification means checking that subcontractors have the required insurance before they start work.
That may include general liability, workers’ compensation, commercial auto, and excess liability.
You also need to track renewal dates. A policy that was active when the job started may expire before the work is finished.
Documentation means keeping clear records.
Save certificates, signed subcontractor agreements, and required endorsements in an organized file for each subcontractor.
These records help you see what insurance was requested and what documents were received.
Risk transfer means using contracts and insurance requirements to explain who is responsible for certain problems.
For example, a subcontractor agreement may require the subcontractor to carry certain coverage and name your company as an additional insured.
Remember that a W-9 form does not prove someone has insurance. It also does not automatically decide if a worker is legally an employee or an independent contractor.
Workers’ compensation rules differ from state to state.
California and Texas, for example, have different requirements.
Talk with your insurance advisor about the rules that apply where you work.
Completed operations coverage can help with certain covered injury or property damage claims caused by your work after the job is finished.
This coverage is usually part of a commercial general liability policy.
It matters because problems can appear long after a contractor leaves the job site.
You may finish a project, receive your final payment, and move on to the next job.
But what if something you installed causes damage months later?
Let’s say you’re a plumbing contractor.
You finish installing pipes in a commercial building.
The owner accepts the work, and your crew leaves.
Six months later, a pipe connection fails.
Water damages the floors and walls.
The owner claims the damage happened because of your completed plumbing work.
Depending on the policy and the cause of the loss, completed operations coverage may help with certain damage.
But there is a limit to what this coverage may do.
General liability insurance is not a promise that your work will never have problems.
If you installed a pipe connection incorrectly, your policy may not pay to fix that connection.
But if the bad connection caused covered damage to other parts of the building, the policy may help with that damage.
These are two different costs.
One is the cost of fixing your own work. The other is the cost of damage that your work caused.
Your policy may treat them differently.
This is why contractors need to understand the exclusions in their general liability policies.
Suppose you’re a general contractor who hires a plumbing subcontractor.
The plumber finishes the work, and the project closes.
Months later, a plumbing problem causes damage.
The owner may bring a claim against your company because you managed the project.
Your insurance and the plumber’s insurance may respond differently.
The answer depends on the policies, the subcontractor agreement, and the cause of the damage.
Some general liability policies also have limits or exclusions that affect subcontracted work.
That’s another reason to check your subcontractors’ coverage before they start.
You should also review any contract requirements for additional insured protection after the work is finished.
Coverage for work in progress may not be the same as coverage for completed work.
Your responsibilities may continue after your crew has left the site.
Let’s say you’re a general contractor bidding on a commercial renovation.
The owner wants to be an additional insured on your policy.
You must provide a certificate of insurance before starting work.
The contract also requires more liability coverage than you currently have, so you need to review your excess liability options.
You’ll be hiring subcontractors, which means you need to check their insurance and workers’ compensation coverage.
You also need to understand your deductibles and the completed operations requirements.
All six terms affect the same job, but each one deals with a different issue.
A certificate doesn’t replace the insurance policy. General liability doesn’t cover every risk. And hiring subcontractors doesn’t remove your need to manage their insurance.
Before you bid, read the insurance section of the contract. Check the required policies, limits, endorsements, and any rules that apply after the work is done.
If something is unclear, ask your insurance advisor to review it.
A short review before the job starts may help you avoid problems later.
You don’t need to know every insurance term to run a successful construction business.
But you should understand the terms that affect your jobs.
Additional insured coverage helps protect certain other parties under a policy. A certificate of insurance shows basic policy information. A deductible is the amount you may have to pay toward a covered loss.
Excess liability provides higher coverage limits. Workers’ compensation helps address covered employee injuries. Completed operations coverage may help with certain claims after the work is finished.
These terms matter most when they appear in a contract for a job you’re planning to take.
At Integrated Commercial Insurance Solutions, Inc., we help contractors review insurance requirements, understand their coverage, and find options that fit their work.
Have a construction contract or insurance requirements you’re not sure about? Send them over. We’ll review them with you.
To request a contractor insurance quote, visit https://icinssolutions.com/request-a-quote/ or call 800-922-9721.
We’re here to help you understand your insurance so you can focus on your next job.
A certificate holder is a person or business that receives a certificate showing your insurance information. An additional insured receives certain protection under your insurance policy. Being listed as a certificate holder does not automatically make someone an additional insured. The policy and its endorsements must provide that protection.
No. A certificate of insurance shows basic information about your policies, but it does not guarantee that every part of your work is covered. Your policy may have exclusions, limits, or conditions that affect a claim. Have your insurance advisor review the job requirements and the actual policies before work begins.
You should not assume you can. If the contract requires higher limits, you may need to arrange more coverage or get the owner to agree to different requirements. Review these details before bidding or starting work. A certificate cannot increase your insurance limits.
General liability insurance generally covers certain claims involving bodily injury or property damage, subject to policy terms. Excess liability insurance adds higher limits above specified underlying policies. It does not automatically cover every claim that the underlying policy excludes.
That depends on state law, the subcontractor’s workers, and the project requirements. General contractors should verify whether subcontractors have the required workers’ compensation coverage before work begins. Missing coverage may create legal or financial exposure for the general contractor.
Not necessarily. Completed operations coverage may help with certain covered injuries or property damage caused by completed work. However, the cost of repairing or replacing defective work itself may be excluded. The policy wording and the cause of the loss determine how coverage applies.
General contractors should collect certificates of insurance, required endorsements, and signed subcontractor agreements. They should also verify the coverage types and limits required for the work. Keep these records organized and track policy expiration dates so coverage can be checked throughout the project.
The best time is before you submit your bid or agree to the job. Your advisor can review required insurance types, coverage limits, additional insured provisions, and completed operations requirements. Finding a missing requirement early gives you more time to address it before work starts.
This article is a collaboration between IC Insurance Solutions, Inc and OpenAI’s ChatGPT. Created on Oct 27, 2026, it combines AI-generated draft material with IC Insurance’s expert revision and oversight, ensuring accuracy and relevance while addressing any AI limitations.
OSHA’s construction standards cover job-site safety requirements, including fall protection, scaffolding, equipment, and other common hazards. This is a useful reference for contractors who want to connect workplace injury risks with their safety responsibilities.
https://www.osha.gov/laws-regs/regulations/standardnumber/1926
This federal resource explains workers’ compensation programs and directs readers to relevant state and federal information. It helps contractors understand why coverage duties and employee injury benefits can differ by location.
https://www.dol.gov/general/topic/workcomp
ACORD provides standardized forms widely used to communicate insurance information, including certificates of insurance. Its forms resource gives contractors and risk managers useful background on the documents they receive and submit during insurance verification.
https://www.acord.org/standards-architecture/acord-forms